
 Most founders and business owners focus almost exclusively on EBITDA multiples, adjusted earnings, and balance sheets when preparing to sell. While the financials set the floor, they miss one of the most critical drivers of a successful exit: buyer perception.
When pricing a business for sale, your primary goal isn’t just to land on a theoretical valuation—it’s to trigger buyer action, generate momentum, and create competition.
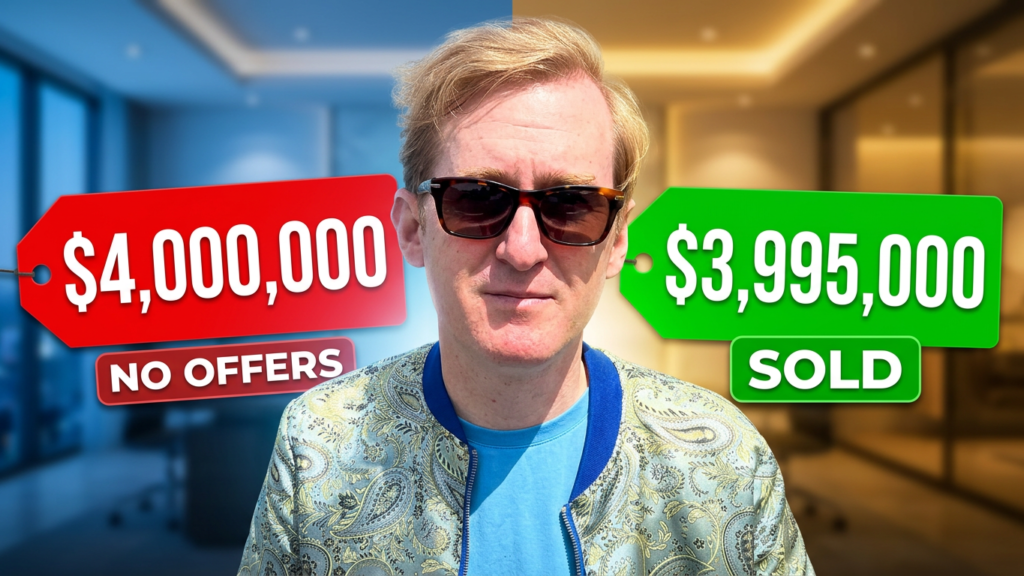
The Seller Strategy: Charm Pricing in M&A ($3,995,000 vs. $4,000,000)
Retailers have used “charm pricing” for decades because human psychology is remarkably predictable. That same behavioral economics principle applies to lower-middle-market M&A.
Pricing a company just under a major psychological threshold—such as listing at $3,995,000 instead of $4,000,000—serves two key functions:
-
Psychological Justification: It gives buyers, investment committees, and lenders an easy internal narrative: “It’s under $4 million.”
-
Search Filter Visibility: Acquirers searching within strict mandate bands (e.g., “up to $4M”) will capture the listing, maximizing initial reach.
That subtle shift in framing drives more initial inquiries, higher confidentiality agreement execution, and earlier offers. In M&A, early competition creates leverage—and leverage is what ultimately secures superior deal structure, lower escrow holdbacks, and better overall terms.
The Buyer Strategy: Leveraging Seller Ego
If you are on the buy side, flipping this psychological framework becomes your secret weapon in competitive bidding scenarios.
Offering $4,000,000 or $4,050,000 on a $3,995,000 listing plays directly into the owner’s ego. For a founder who has poured years into building an enterprise, crossing that round threshold is deeply symbolic.
A slightly higher nominal price allows the seller to tell their family, network, and advisors that they exited for “over asking” and “over $4 million.” In tight negotiations, granting the seller that psychological win can often buy you concessions on higher-value terms, such as seller notes, transition timelines, or working capital pegs.
The Core Emotional Drivers of M&A
At its core, deal-making stripped of spreadsheet models comes down to two primary emotional motivators:
-
Fear on the Buyer’s Side: Fear of missing out on a pristine asset, or fear of overpaying without sufficient downside protection.
-
Ego on the Seller’s Side: The need for validation after years of risk-taking, operational sacrifice, and value creation.
To succeed in M&A, master the mindset swap: think like an acquirer when you’re selling your business, and think like a founder when you’re buying one.
#DavidMayfair #BusinessBroker #MergersAndAcquisitions #BusinessValuation #ExitStrategy #DealMaking #SalesPsychology #Entrepreneurship